DeployCo Comparison Matrix: Every AI Deployment Provider Side by Side
The lab-backed DeployCos, the hyperscaler units, Palantir, the independents, the systems integrators and an in-house team, compared on the same columns: money committed, embedded engineers, pricing, model choice, delivery model, named customers, partners, strengths and watch-outs. Every row carries its sources and a last-verified date. Filter it to your situation, or hide columns you do not need.
The matrix
"Not disclosed" means the provider has not published that number. Announced deals are labeled as announced; nothing pending is shown as closed.
Showing 9 of 9 providers
| Provider | Type | Commitment | Embedded engineers | Pricing model | Model choice | Delivery model | Named customers | Partners | Strengths | Watch-outs | Sources |
|---|---|---|---|---|---|---|---|---|---|---|---|
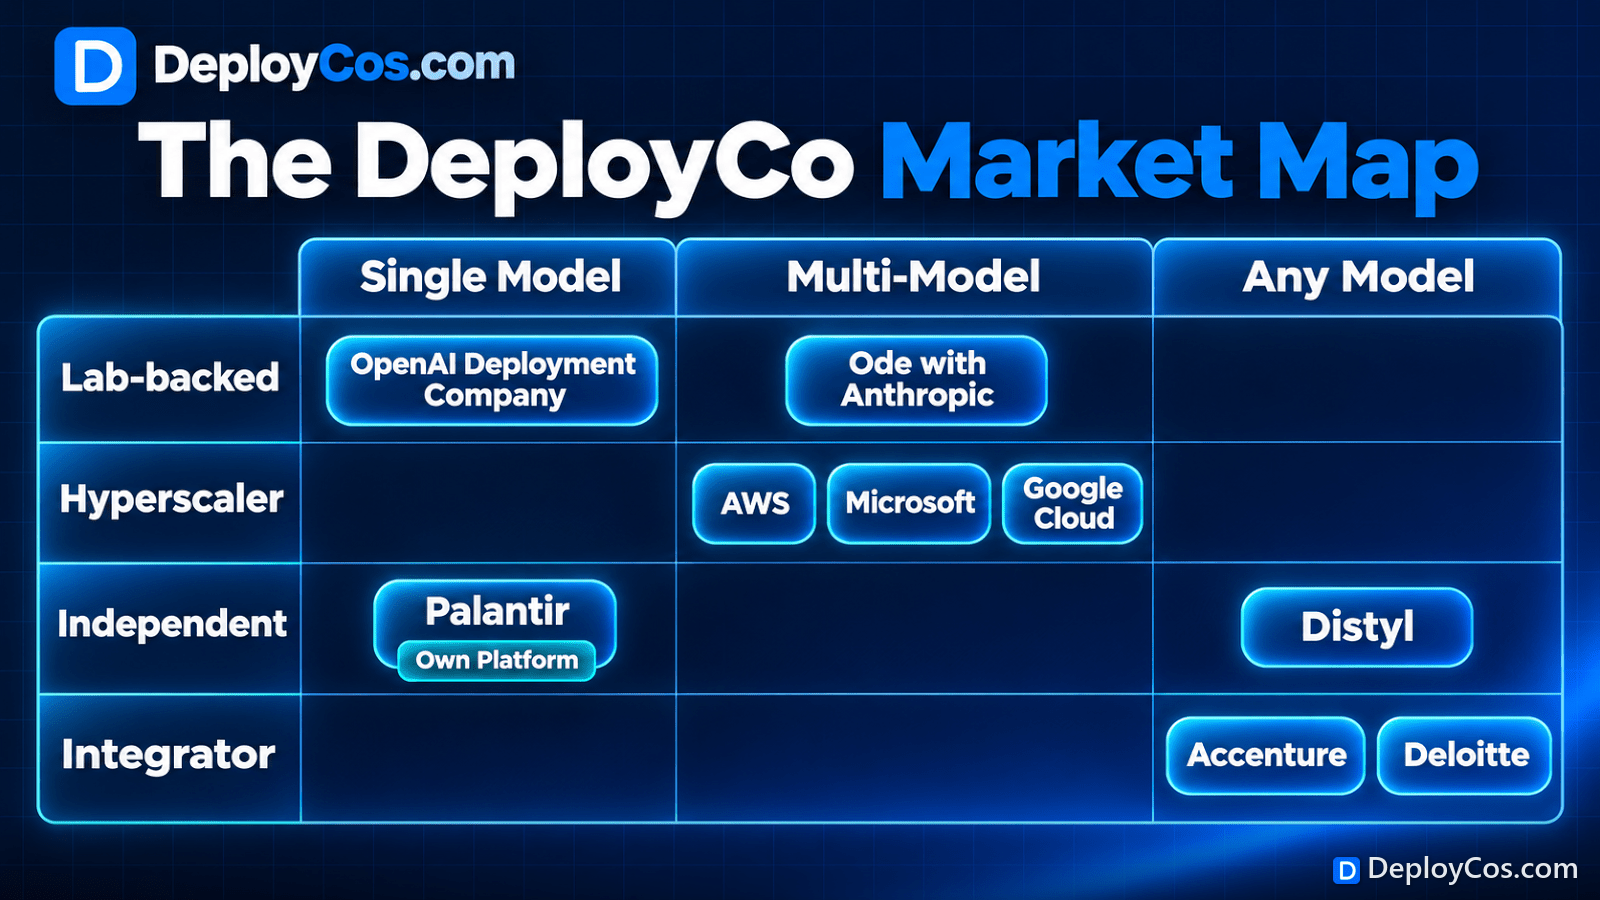
| OpenAI Deployment CompanyLast verified 11-08-2026 | lab-backed DeployCo | $4,000,000,000+ initial investment (announced) | About 150 via the Tomoro acquisition (announced; closing not confirmed) | Not disclosed | single model | A diagnostic, then a few priority workflows built and run in production by embedded engineers | BBVA, John Deere, Tesco (Tomoro client), Virgin Atlantic (Tomoro client) | TPG, Advent, Bain Capital, Brookfield, Bain & Company, Capgemini, McKinsey & Company | The best-funded lab-backed unit, with direct access to OpenAI engineers and its backers' portfolio companies as ready customers. | Builds on OpenAI models as announced, and a reported 17.5% minimum return to backers (Financial Times; Reuters could not confirm) pushes it to scale billable work. | OpenAI launches the OpenAI Deployment Company; The Next Web: OpenAI DeployCo joint venture; Axios: OpenAI deployment arm to acquire Northslope |
| Ode with AnthropicLast verified 11-08-2026 | lab-backed DeployCo | $1,500,000,000 (press-reported; not in Anthropic's announcement) | About 100 engineers at launch (TechCrunch) | Not disclosed | multi-model | Small engineering teams build custom Claude-powered systems with Anthropic Applied AI engineers; Claude-first, other models where required | LogicGate (partnership), PointClickCare (partnership) | Anthropic Applied AI, Blackstone, Hellman & Friedman, Goldman Sachs | Aimed at the mid-market that large consultancies underserve, with an engineering-heavy team and a model-flexible stance. | Capital, revenue and acquisition prices are undisclosed or press-reported only, and the Claude-first policy may narrow at scale. | Anthropic: Building a new enterprise AI services company; The Next Web: Ode, Anthropic and Blackstone bet on implementation; Alternatives Watch: Ode with Anthropic launches |
| Palantir (forward deployed engineers, AIP bootcamps)Last verified 11-08-2026 | software vendor FDE | Not disclosed | Not disclosed | Negotiated platform subscription; embedded engineering often bundled (no published price) | own platform | Forward deployed engineers deploy and extend Foundry and AIP at the customer; AIP bootcamps open the sale | Not disclosed | Not disclosed | The reference FDE model; Q3 2026 revenue of $2,313,000,000 (up 96%) with US commercial revenue of $984,000,000 (up 148%). | You adopt Palantir's platform, and FDE services revenue is not reported separately from licenses. | Palantir Q3 2026 results (Form 8-K, Ex. 99.1); Palantir Form 10-Q, quarter ended 09-30-2026 |
| AWS Forward Deployed EngineeringLast verified 11-08-2026 | hyperscaler unit | $1,000,000,000 | Reported as hundreds by some outlets and thousands by others | Fixed, outcome-based pricing rather than billable hours | multi-model | Pods of five or six engineers with one customer for about 45 days, ending with an exit plan | Allen Institute, Cox Automotive, National Football League, National Basketball Association, Ricoh | AWS partner network | The only hyperscaler unit that states fixed, outcome-based pricing, plus a defined exit plan and a multi-model catalog. | Engagements build on AWS, so the work pulls toward AWS consumption. | Constellation Research: AWS launches forward deployed engineering unit; The Next Web: AWS commits $1bn to forward deployed engineers |
| Microsoft Frontier CompanyLast verified 11-08-2026 | hyperscaler unit | $2,500,000,000 | About 6,000 engineers and industry experts, largely existing staff | Not disclosed | multi-model | Embedded engineers and industry experts build, launch and keep improving AI systems | LSEG, Unilever, Land O'Lakes | Accenture | The largest stated headcount of any 2026 entrant, and Microsoft says customers should not be locked into one model. | No published pricing or delivery method, and most of the 6,000 are existing staff. | TechRadar: Microsoft is spending $2.5bn on deploying AI engineers; HCAMag: Microsoft invests $2.5 billion to help companies embed AI |
| Google Cloud partner-embedded FDEsLast verified 11-08-2026 | hyperscaler unit | $750,000,000 partner fund | Not disclosed | Not disclosed; partner funding, proofs of concept and usage incentives | multi-model | Google engineers embed alongside systems integrators, who deliver most of the work | Not disclosed | Accenture, Capgemini, Cognizant, Deloitte, HCLTech, TCS, Distyl, Northslope | Broad reach through the partner ecosystem without a large Google delivery arm. | Not a standalone unit, no headcount target or pricing, and press partner lists vary. | Google Cloud commits $750 million to partners' agentic AI development; ARN: Google Cloud launches US$750M agentic AI partner fund |
| Distyl AILast verified 11-08-2026 | AI-native startup | $175,000,000 Series B at a $1,800,000,000 valuation (09-2025 funding) | Not disclosed | Not disclosed | any | Its Distillery platform plus embedded teams for Fortune 500 clients | Not disclosed | Google Cloud | Palantir-style embedded delivery without lab ownership, so it can pick whichever model fits. | Customer names and profitability claims are not independently confirmed. | Fenwick: Distyl AI $175M Series B at $1.8B valuation; PYMNTS: Distyl raises $175 million |
| Global systems integrators (Accenture, Deloitte and peers)Last verified 11-08-2026 | systems integrator | About $11,500,000,000 cumulative advanced AI bookings at Accenture through Q1 FY26 (last disclosed) | Not disclosed | Time and materials, fixed fee or managed service | any | Consulting-led teams for strategy, integration and change management; also co-deliver for the lab and hyperscaler programs | Not disclosed | OpenAI Frontier Alliance, Anthropic partner network, Google Cloud, Microsoft | Scale, existing client relationships and neutrality across models. | Accenture stopped disclosing advanced AI bookings after Q1 FY26, and consulting-led delivery can mean fewer engineers per dollar. | Benzinga: Accenture says AI demand is rising but scale remains limited; Fortune: OpenAI partners with McKinsey, BCG, Accenture and Capgemini |
| In-house AI teamLast verified 11-08-2026 | in-house | Not disclosed | Not disclosed | Salaries, tools and model spend you control | any | Your own engineers build and run AI systems with no outside dependency | Not disclosed | Not disclosed | Full control, no vendor dependence, and the skills stay in the company. | Slow to hire, and few organizations have scaled AI on their own (McKinsey). | McKinsey: AI at work but not at scale; McKinsey: The state of AI |
How to read the matrix
Commitment is the money a provider or its backers announced for the unit, not revenue. The OpenAI Deployment Company's more than $4 billion is an initial investment pool; Microsoft's $2.5 billion and AWS's $1 billion are internal budgets; Google Cloud's $750 million is a partner fund.
Model choice is the single most important column for a buyer. A "single model" provider builds on its owner's models; "multi-model" providers have a preference but will use others; "any" means no model maker owns the provider. Palantir is marked "own platform" because you adopt Foundry and AIP. See Risks and Debates for why lock-in matters.
Pricing is almost never published. AWS is the only hyperscaler unit that states fixed, outcome-based pricing. For everyone else, ask for a production cost per task in writing, and model it with the ROI calculator.
Which type fits which buyer
| Type | Best when | Think twice when |
|---|---|---|
| Lab-backed DeployCo | You want the newest frontier capabilities first and accept one lab's models | You must stay model-neutral |
| Hyperscaler unit | You are mostly on one cloud and want platform credits and multi-model choice | Your estate spans several clouds or on-premises systems |
| Software vendor FDE (Palantir) | You will standardize on the vendor's data platform | You do not want platform dependence |
| AI-native independent | You want embedded engineering with no model maker in the room | You need a large firm's balance sheet and global reach |
| Systems integrator | The work is a company-wide change program | You need a few engineers shipping one workflow fast |
| In-house team | You have time and engineers, and want the skills to stay | You need production results this quarter |
Not sure? Answer ten questions in the decision tool, or check your readiness first.
Download the data
The matrix is open data under CC BY 4.0: reuse it with a credit to DeployCos.com. The same rows feed the one-page landscape cheat sheet.
Frequently asked questions
Which AI deployment company is the biggest?
By announced money, the OpenAI Deployment Company, with more than $4 billion of initial investment announced 05-11-2026. By stated headcount, Microsoft's Frontier Company, with about 6,000 engineers and industry experts, most of them existing staff. By revenue from embedded engineering, Palantir, though it does not report FDE services separately.
Which providers are model-neutral?
The hyperscaler units are multi-model, independents such as Distyl and the systems integrators are not owned by a model maker, and Ode with Anthropic is Claude-first but says it will use other models where required. The OpenAI Deployment Company builds on OpenAI models as announced.
Why are prices missing?
Because almost no provider publishes them. The matrix shows only what a provider or a credible report has stated. Use the request-for-proposal questions in the downloads to get prices in writing.
How often is the matrix updated?
Every page is validated roughly twice a week or more. Pages show a last-reviewed date, and the comparison data shows a last-verified date per provider. We do our best to keep DeployCos.com the most up-to-date, comprehensive reference on deployment companies and their history. Material changes appear on What's New.